Get everyone inside safely, then photograph the damage from the ground and inside your attic before you touch anything. If water is actively coming in or you can see exposed decking, call a licensed roofer for emergency tarping rather than waiting. Notify your insurance company the same day if possible, and schedule a professional inspection within the week. Everything else, including the repair-versus-replace decision, comes after those four steps.
TL;DR:
- Emergency tarping is advisable immediately if active water intrusion, exposed decking, or safety hazards are present, with costs ranging from $200 to $1,500.
- Wind damage often lifts shingles and exposes underlayments, while hail bruises shingles and dents metal; some damage remains invisible from ground inspections.
- Proper documentation, including timestamped photos and detailed contractor estimates, is essential to support insurance claims and prevent denials.
- Filing within 30 to 60 days, understanding policy differences between ACV and RCV, and verifying coverage details improve settlement chances.
- Full roof replacement is more likely when multiple slopes are damaged, the roof is older, or critical components like decking are compromised.
Table of Contents
- Step-by-Step Storm Damage Roof Repair: The First 24 to 48 Hours
- Types of Storm Damage and How Each Shows Up on Your Roof
- How to Inspect and Document Storm Damage Properly
- When Should You Get Emergency Tarping After Storm Damage?
- Insurance Claims: ACV, RCV, and What Gets You Denied
- Repair or Replace: How Adjusters Actually Decide
- Choosing a Reputable Contractor After Storm Damage
- Storm Damage Roof Repair Costs and Realistic Timelines
- Publisher Perspective: Practical Recommendations From Budget Roofing and Siding
- Get Help With Storm Damage Roof Repair in Central Texas
- Sources
- FAQ
Step-by-Step Storm Damage Roof Repair: The First 24 to 48 Hours
The first two days after a storm determine how strong your insurance claim will be and whether small problems turn into big ones. Move fast, but move in the right order.
- Check for interior hazards first. Sagging ceilings, sparking outlets, or a strong smell of gas mean you call emergency services before anything else.
- Walk the exterior from the ground. Photograph missing or lifted shingles, granules pooling in gutters or downspouts, dented vents, and any debris on the lawn or roofline.
- Get into the attic if it's safe. Look for wet insulation, fresh water stains on the underside of the decking, and daylight coming through anywhere it shouldn't.
- Move furniture and belongings away from leak points, and photograph ceiling stains before you blot or contain them.
- Decide who to call. Active flooding or structural danger means emergency services or an emergency tarping crew immediately; everything else can wait for a scheduled roofer inspection and a call to your insurer.
- Log the date and time, save any local weather alerts, and note if neighbors had similar damage. This corroboration helps later if a claim gets questioned.
Pro Tip: Text yourself a quick timestamped photo the moment you spot damage. Insurance adjusters weigh dated evidence far more heavily than photos taken days later with no clear timeline.
Types of Storm Damage and How Each Shows Up on Your Roof
Not all storm damage looks the same, and some of the worst damage is invisible from your driveway.
- Wind damage lifts shingle edges, creases tabs, exposes underlayment, and can pop ridge caps off entirely.
- Hail damage bruises shingles and knocks granules loose, often leaving dents in soft metal like vents and gutters long before you notice anything on the shingles themselves.
- Debris impact punctures the roof surface, cracks decking, and displaces flashing around chimneys and skylights.
- Water and ice damage shows up as attic moisture, ceiling stains, and, in colder climates, ice-dam ridges or ponding along low slopes.
Wind can break a shingle's adhesive seal without tearing it loose, so it looks fine from the ground but leaks the next time it rains. Hail can bruise a shingle mat beneath the granule layer with no visible hole at all, which is exactly why ground-level inspections miss so much real damage.
How to Inspect and Document Storm Damage Properly
A strong insurance claim rests on documentation, not memory. Before any permanent repair happens, you need a paper trail a claims adjuster can't argue with.
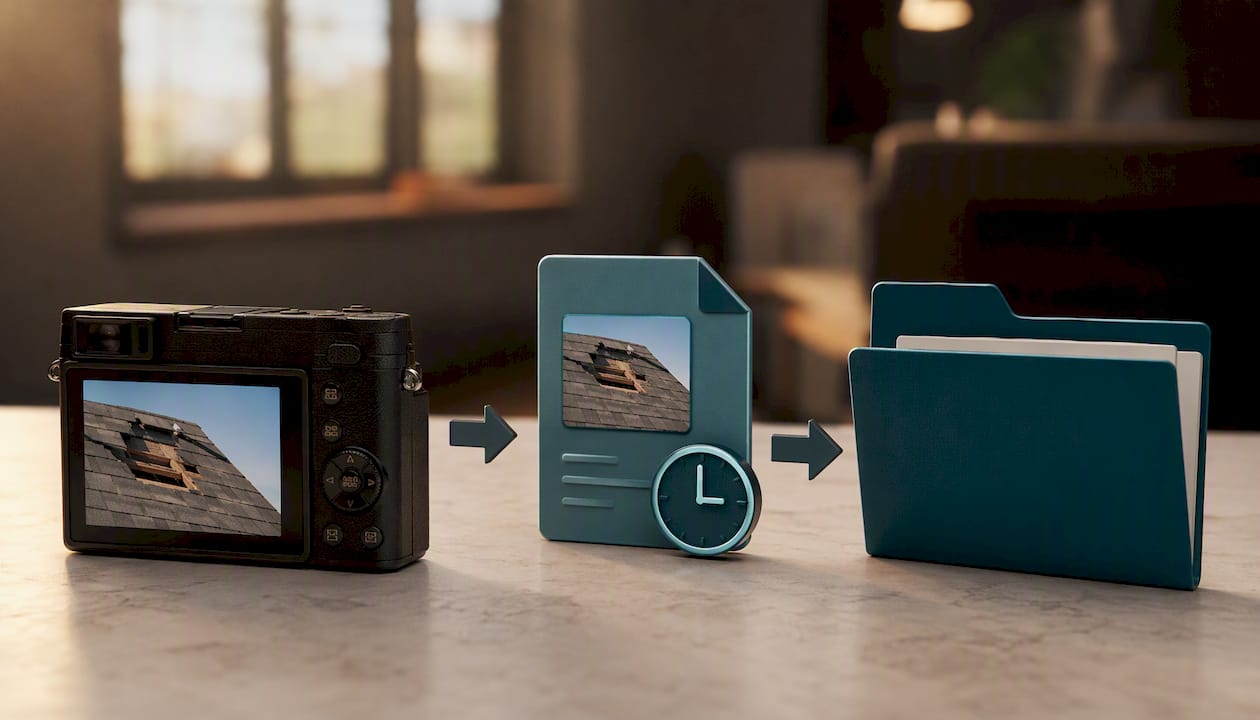
- Take close-up shots of individual damaged shingles, vents, and flashing, plus wider context shots showing the whole roof plane and any debris in the yard.
- Check the attic for wet insulation, decking stains, and moisture patterns that map back to specific leak points on the roof.
- Ask your contractor for a line-item estimate that separates materials, labor, a decking replacement allowance, and warranty terms, not a single lump-sum number.
- Hold off on permanent repairs until documentation is complete, and photograph any temporary work both before and after it's done.
Top homeowner guidance consistently stresses documenting damage before cleanup and getting an independent inspection rather than relying solely on the insurance company's own adjuster.
Pro Tip: Ask your contractor to date-stamp every inspection photo directly in the file metadata. Adjusters and insurance reviewers trust embedded timestamps more than a photo you attach to an email later.
When Should You Get Emergency Tarping After Storm Damage?
Tarping makes sense when there's an active leak, exposed decking, or a safety concern like a partially detached section of roofing. It's a stopgap, not a fix, but it's often the smartest money you'll spend after a storm.
- Active water intrusion into living space or the attic
- Visible decking exposed to open sky
- Loose materials that could fall or blow off in the next storm
Professional tarping typically runs $200 to $1,500, depending on roof size, pitch, and access difficulty. That range looks steep until you compare it to the alternative: continued water intrusion can push interior restoration costs into the thousands, covering drywall, insulation, flooring, and mold remediation. Always document temporary work with before-and-after photos and keep every receipt. Your insurer will often reimburse reasonable mitigation costs, but only if you can prove what was done and when. Use an experienced tarping crew. A poorly secured tarp can rip loose in the next wind event and cause more damage than the original storm.
Insurance Claims: ACV, RCV, and What Gets You Denied
Your policy type determines how much you actually collect, and most homeowners don't find out the difference until it's too late.
- Actual Cash Value (ACV) policies pay the depreciated value of your roof, meaning a 12-year-old roof gets paid out at a fraction of replacement cost.
- Replacement Cost Value (RCV) policies pay to replace the roof with new materials, though many RCV policies hold back a depreciation amount until the work is completed and verified.
- File within 30 to 60 days of the storm whenever possible. Waiting longer gives insurers room to argue the damage happened some other way or wasn't storm-related at all.
- Expect an adjuster visit within a week or two of filing. Independent contractor documentation, including your own dated photos and a written estimate, gives the adjuster less room to lowball the claim.
- Watch for common denial reasons: pre-existing wear misattributed to the storm, delayed reporting that raises suspicion, or improper temporary repairs that made the damage worse.
Pro Tip: Pull your policy declarations page before the adjuster arrives and confirm whether you have ACV or RCV coverage. Knowing this in advance changes how you negotiate the settlement.
Repair or Replace: How Adjusters Actually Decide
A repair is usually the right call when the damage is localized to one slope, the roof is under 10 to 15 years old, and matching shingles are still available from the manufacturer. Replacement becomes the likely outcome when multiple roof slopes show damage, hail impact counts meet your carrier's specific threshold, the roof is near the end of its expected lifespan, or the decking underneath is compromised.
- Discontinued shingle lines force a full replacement even for otherwise minor damage, since mismatched patches hurt resale value and violate some manufacturer warranties.
- A roof with a documented maintenance history tends to get more favorable treatment from adjusters than one with no records.
- Ask your contractor directly whether the decking passed inspection, and ask the adjuster what specific hail-count or damage-percentage threshold triggers full replacement under your policy.
Choosing a Reputable Contractor After Storm Damage
Storms bring legitimate roofers and traveling scam crews to the same neighborhoods at the same time, and it's not always obvious which is which.
- Confirm the contractor holds an active license, carries liability insurance, and has a physical local address, not just a phone number.
- Ask for references from jobs completed in your area within the past year.
- Require a dated, photo-backed inspection report and a line-item estimate before signing anything.
- Get at least two estimates so you can compare materials, warranty length, and pricing side by side.
- Walk away from anyone demanding full payment upfront or pressuring you to sign on the spot.
Pro Tip: A contractor who won't put the decking allowance and material brand names in writing on the estimate is a red flag, no matter how good the verbal pitch sounds.
Storm Damage Roof Repair Costs and Realistic Timelines
Costs vary widely depending on how much of the roof is affected and whether hidden damage shows up once the shingles come off.
| Repair type | Typical cost range | Typical timeline |
|---|---|---|
| Emergency tarping | $200–$1,500 | Same day to 24 hours |
| Minor leak or shingle repair | $150–$400 | 1–2 days |
| Major hail or wind repair | $1,000–$5,000+ | 1–3 weeks (materials, scheduling) |
| Full roof replacement | Varies by roof size and material | 3–6 weeks (permits, lead times) |
A $500 emergency tarp can prevent $3,000 to $6,000 in interior restoration costs if water intrusion continues for even a few more days. Hidden decking rot or mold discovered mid-repair almost always adds both cost and time, and permit approval or material back orders can stretch a straightforward job into a multi-week project.
Publisher Perspective: Practical Recommendations From Budget Roofing and Siding
The homeowners who come out ahead after a storm follow the same sequence every time: stabilize, document, inspect, scope, then repair. Skipping straight to a signed contract before documentation is complete is how good claims turn into denied ones. Get more than one estimate and compare them line by line, not just by the bottom-line number. Local material matching and fast response time matter more than people expect, especially across Central Texas service areas where shingle availability and permit timelines vary by county.
— Dan
Get Help With Storm Damage Roof Repair in Central Texas
A reliable roofing and siding company gives homeowners a direct path from storm damage to a finished repair, emphasizing a best price guarantee and straightforward advice to collect multiple estimates before signing anything.
The company handles the full sequence storm damage requires: inspection, emergency tarping, insurance claim coordination, and either targeted repairs or full replacement depending on what the roof needs. Its Insurance Made Easy service walks homeowners through adjuster visits and claim documentation so nothing gets missed or underpaid. For roofs where siding also took a hit from wind-driven debris, the siding repair and replacement team handles that in the same visit. If your roof took a hit in the last storm, request a free inspection and get a written, line-item estimate before you commit to any repair.
Sources
Verify storm dates and severity through NOAA's official storm records. Manufacturer and independent guidance from Owens Corning, GAF, and This Old House covers homeowner-facing storm response and safety steps in more depth.
- Storm Damage Roof Repair: What to Do | CPS
- Emergency Roof Repair Cost 2026: $250–$3,200 + What to Do First
- Roof Storm Damage Checklist What To Do After A ... - Owens Corning
FAQ
What Should You Do First if a Roof Is Damaged in a Storm?
Get everyone inside safely and check for interior hazards like sagging ceilings or exposed wiring first. Then photograph the damage from the ground and attic, arrange emergency tarping if there's active leaking, and notify your insurer the same day.
How Much Does It Cost to Repair Storm Damage to a Roof?
Minor repairs often run $150 to $400, while emergency tarping typically costs $200 to $1,500 depending on roof size and access. Major hail or wind repairs commonly land between $1,000 and $5,000 or more, and full replacements cost significantly more depending on roof size and material.
Who Should You Call for Storm Damage Roof Repair?
Call emergency services first if there's a structural or safety hazard, then a licensed local roofer for tarping and inspection. Budget Roofing and Siding offers free inspections across its Central Texas service areas and can coordinate directly with your insurance adjuster.
Will Insurance Cover Roof Damage From a Storm?
Most homeowner policies cover sudden storm damage from wind, hail, and debris, though coverage depends on whether you have an ACV or RCV policy and whether you filed within your insurer's reporting window. Claims get denied most often for pre-existing wear, delayed reporting, or improper temporary repairs, so documentation before cleanup matters more than almost anything else in the process.